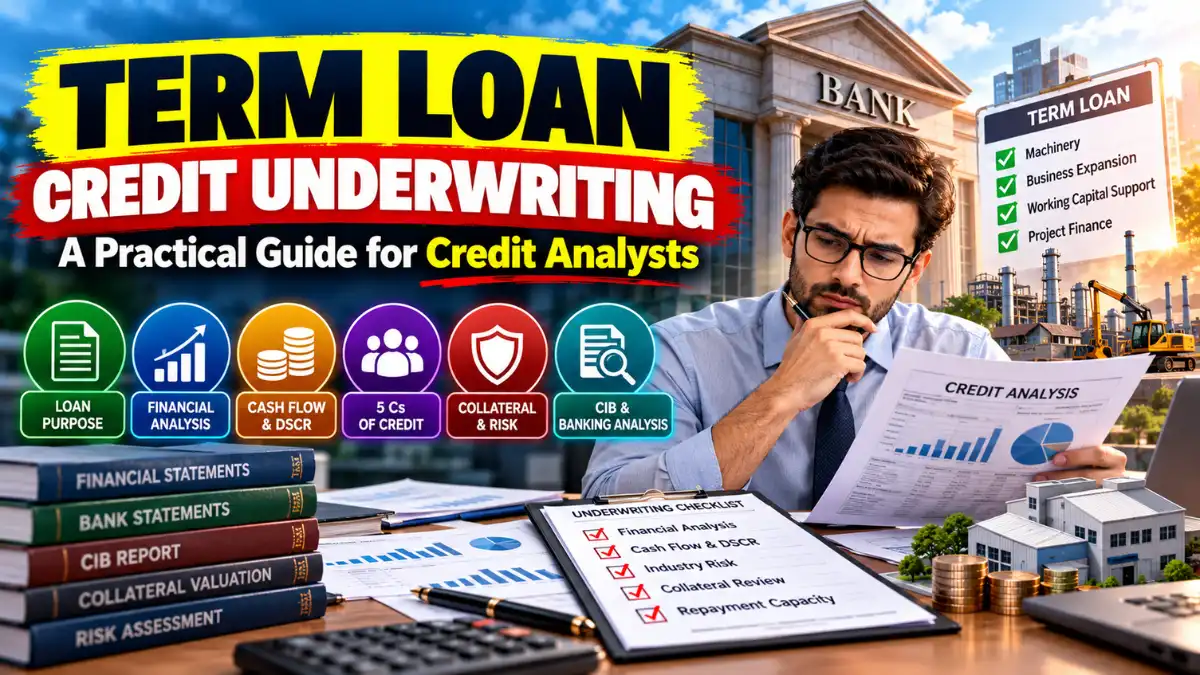
Term Loan Credit Underwriting: A Practical Guide for Credit Analysts
Credit underwriting is not simply the exercise of checking documents, calculating ratios, or confirming the value of collateral. A good credit analyst must answer a much more important question:
“If the borrower faces stress after disbursement, where will the money come from to repay the bank?”
This is why strong underwriting connects the borrower’s character, business model, banking behavior, financial performance, cash flow, industry risk, loan purpose, repayment structure and security into one coherent credit story.
Bangladesh Bank’s credit-risk guidance emphasizes a structured credit assessment and risk-grading process, while Basel principles similarly expect banks to assess both the borrower’s ability and willingness to repay and to continue monitoring the exposure after sanction.
The following framework is designed to address the areas where credit analysts most frequently become confused.
1. Start with the Loan Purpose-Not the Collateral
The first question should not be, “What security is available?”
It should be:
“Why does the borrower need this money, and will the proposed facility actually solve that need?”
A term loan for machinery, for example, should normally be linked to a productive asset whose expected cash generation supports repayment. A loan for factory expansion should be supported by realistic capacity-utilization and sales assumptions.
Consider a manufacturer requesting BDT 10 million to purchase a new production line. If the existing factory is operating at only 45% capacity and the borrower cannot explain how additional output will be sold, the availability of land worth BDT 30 million does not automatically make the proposal strong.
This is one of the most important underwriting principles:
Collateral reduces loss severity; it does not create repayment capacity.
2. Documents: Complete Does Not Mean Reliable
A credit file may contain every document on the checklist and still represent a weak borrower.
The analyst should examine:
- Identity and ownership documents
- Tax returns and tax computation
- Business registration and licenses
- Bank statements
- Audited and management financial statements
- Existing loan statements
- Credit bureau/CIB information
- Board resolutions where applicable
- Security and ownership documents
- Insurance and valuation reports
- Relevant regulatory approvals
But the real question is whether the documents tell the same story.
Suppose reported annual sales are BDT 100 million, while banking transactions indicate only BDT 35 million of regular business receipts. That does not automatically prove manipulation—but it creates a question that the analyst must resolve.
Similarly, if tax-return income, audited profit and bank turnover are materially different, the analyst should understand why before recommending the facility.
3. Bureau/CIB Analysis: A Good Score Is Not a Clean Credit Story
One common analytical mistake is to treat a bureau score or CIB report as the final answer.
It is only one part of the assessment.
Look for:
- Recent loan enquiries
- Multiple borrowings within a short period
- Past defaults
- Rescheduled or restructured facilities
- Write-off history
- Excessive utilization
- Frequent new facilities
- Irregular repayment patterns
- Liabilities not properly reflected in the proposal
A borrower may have a satisfactory current status but still show signs of increasing financial pressure.
Example: A borrower has recently obtained three facilities from different institutions. There is no current default, but the sudden increase in borrowing coincides with declining business margins.
The correct question is not:
“Is the borrower currently regular?”
It is:
“Why has the borrower suddenly needed additional debt?”
This distinction often separates mechanical checking from genuine underwriting.
Bangladesh Bank describes credit risk grading as useful both before sanction and after sanction, including decisions about exposure, pricing, facility structure and risk mitigation.
4. Banking Analysis: Follow the Money
Financial statements tell you what management reports. Bank statements show how money actually moves.
Analyze:
Average balance → credit turnover → debit turnover → cash deposits → cheque returns → overdraft behavior → loan servicing → major counterparties.
A common confusion arises when analysts see high deposits and assume strong cash flow.
High deposits are not necessarily evidence of genuine business turnover.
For example, a company may show BDT 80 million of monthly credits, but if most credits are immediately followed by transfers to related parties, inter-bank movements or reversals, the underlying operating cash generation may be much weaker.
Similarly, a salary account where the salary is credited and withdrawn immediately tells a different story from a stable savings pattern.
The analyst should distinguish:
Operating inflow ≠ total bank credits.
5. Financial Analysis: Profit Is Not Cash
This is perhaps the most important concept in term-loan underwriting.
A borrower can report:
- Strong sales
- Good gross profit
- Positive net profit
and still struggle to repay debt.
Why?
Because profit can be tied up in:
- Receivables
- Inventory
- Advances
- Capital expenditure
Consider:
Sales = BDT 100 million
Net profit = BDT 8 million
Receivables increase = BDT 15 million
Inventory increase = BDT 10 million
The borrower may report BDT 8 million profit, but substantial cash has been absorbed by working capital.
Therefore, the analyst must move from:
Profitability → Cash conversion → Debt servicing capacity.
Consider revenue quality, gross margin, operating margin, net margin, ROE/ROCE, leverage, working-capital cycle, and cash flow together.
6. DSCR: Where Many Analysts Go Wrong
A good question for DSCR is:
Does the business generate enough cash to service its debt?
A very simplified definition is:
Cash available for debt service ÷ Total debt service
Say,
Annual cash available for debt service = BDT 15 million
Annual principal + interest obligation = BDT 10 million
DSCR = 1.50x
This indicates a reasonable cushion under the assumed cash flow.
But analysts should avoid blindly applying one universal threshold. A 1.20x DSCR may be comfortable in one stable business but insufficient in a highly volatile business.
More importantly, check whether the numerator represents real sustainable cash generation.
A DSCR calculated using an aggressive projected profit can look excellent on paper while actual repayment capacity remains weak.
7. FOIR, Current Ratio and TOL/TNW Need Context
Ratios should support judgment—not replace it.
FOIR = Fixed Obligations ÷ Income
It is particularly useful in individual/retail lending, but the appropriate threshold depends on the product and policy.
Current Ratio = Current Assets ÷ Current Liabilities
A current ratio of 1.50x may look stronger than 0.90x, but the analyst should examine the quality of current assets. BDT 20 million of old receivables is not equivalent to BDT 20 million of cash.
TOL/TNW = Total Outside Liabilities ÷ Tangible Net Worth
Suppose:
Total outside liabilities = BDT 40 million
Tangible net worth = BDT 20 million
TOL/TNW = 2.00x
That may appear manageable, but the analyst should investigate whether the net worth is supported by genuine retained earnings or inflated by revaluation and other non-cash items.
8. Collateral: Value Is Not the Same as Recoverable Value
This is another area where analysts frequently become confused.
Let us assume that the property has a forced sale value of BDT 20 million and the financing proposed is a loan of BDT 12 million.
Simple LTV:
12 ÷ 20 = 60%
That looks comfortable.
But ask:
- Is ownership clear?
- Is the property legally transferable?
- Is there any existing charge?
- Is the title disputed?
- Is mutation completed?
- Is construction approved?
- Is the valuation current?
- Is insurance required?
- Can the bank actually enforce the security?
Collateral only becomes meaningful when the bank can legally and practically realize it. Basel’s credit-risk mitigation framework similarly emphasizes enforceable rights over collateral and the ability to take possession or liquidate it when required.
Therefore:
Security coverage ≠ repayment capacity.
A fully secured bad loan can still become a bad loan.
9. The 5 Cs: Use Them as a Thinking Framework
The traditional 5 Cs of Credit remains useful:
Character – Does the borrower demonstrate integrity and repayment discipline?
Capacity – Can the borrower generate sufficient cash to repay?
Capital – How much of the borrower’s own money is invested?
Collateral – What protection exists if repayment fails?
Conditions – What external factors could affect the business?
The biggest analytical mistake is giving excessive weight to collateral while underweighting capacity and character.
A borrower with strong collateral but weak cash flow may represent a recovery-dependent transaction.
A borrower with moderate collateral but exceptionally strong and transparent cash generation may present a fundamentally different risk profile.
10. Industry Risk Can Change the Meaning of the Numbers
The same financial ratio can mean different things in different industries.
A trading business may naturally operate with high receivables and inventory. A service company may have limited inventory but high dependence on human resources. A construction company may have project-based cash flows, while a manufacturing company may require significant working capital.
Therefore, never analyze a borrower in isolation from its industry.
Consider:
- Demand outlook
- Competition
- Raw-material price volatility
- Regulatory risk
- Import dependency
- Foreign-exchange exposure
- Customer concentration
- Supplier concentration
- Seasonality
- Technology risk
- Entry barriers
Bangladesh Bank’s Internal Credit Risk Rating framework recognizes sector differences by using industry-specific assessment templates rather than treating every borrower identically.
11. Projected Cash Flow: The Most Dangerous Place for Optimism
Credit analysts often face aggressive projections.
A borrower may present:
Current sales: BDT 100 million
Projected sales: BDT 160 million
The analyst should ask:
Why will sales increase by 60%?
Look for evidence:
- Confirmed orders
- New contracts
- Capacity expansion
- Additional distribution channels
- Historical growth
- Market demand
- Production capacity
- Working-capital availability
Do not accept:
“Sales will increase because the new machine will increase production.”
Production capacity does not automatically create demand.
A sound projection connects:
Investment → Capacity → Sales → Gross Margin → Operating Cash Flow → Debt Service.
12. Repayment Source Must Be Explicit
Every term loan should have a clearly identified primary repayment source.
For example:
Primary source: Operating cash flow
Secondary source: Liquidation of eligible security
Contingency: Sponsor support, additional equity or other acceptable source
If the analyst cannot clearly explain where the installments will come from, the proposal is not yet fully underwritten.
The purpose of collateral is primarily to provide protection if the primary repayment mechanism fails—not to become the primary repayment plan.
13. Common Red Flags That Should Trigger Questions
Red flags should not necessarily raise a “no” response. In other words, red flags are not deal killers. They should simply raise questions. They should trigger investigation.
Important warning signals include:
- Multiple recent loan enquiries
- Sudden increase in borrowing
- Large unexplained cash deposits
- Frequent related-party transfers
- Circular or layered transactions
- Cheque/EMI returns
- Persistent overdrawing
- Immediate withdrawal of credited funds
- Frequent address changes
- Tax filing inconsistencies
- Large differences between declared sales and banking turnover
- Declining margins despite rising sales
- Increasing receivable days
- Inventory growing faster than sales
- Litigation over property or business
- Heavy dependence on one customer
- Excessive reliance on projected rather than historical cash flow
The key principle is:
A red flag is a question—not automatically a conclusion.
14. The Final Credit Decision: Approve, Condition, Refer or Reject
At this point, the credit analyst should have enough information to respond to six basic questions:
- Why does the borrower need the loan?
- How will the loan generate or support repayment?
- What is the borrower’s existing leverage?
- What could cause repayment failure?
- How strong is the bank’s secondary protection?
- What conditions can reduce the identified risks?
The decision may therefore be:
Approve – Risk is acceptable within policy.
Approve with Conditions – Risk is acceptable if specific mitigants are imposed.
Refer/Escalate – The case requires higher authority because of size, complexity or unusual risk.
Reject – Repayment capacity, transparency, legality, policy compliance or overall risk is unacceptable.
Bangladesh Bank’s credit-risk guidance emphasizes defined lending policies, credit assessment, approval processes, monitoring and segregation of responsibilities; these are fundamental controls rather than merely administrative requirements.
15. The Golden Rule for Every Credit Analyst
A strong credit analyst does not ask only:
Can we approve this loan?
The better questions are:
- What can go wrong?
- What evidence supports repayment?
- What assumption am I relying on?
- What happens if sales fall by 20%?
- What happens if receivable collection is delayed?
- What happens if the borrower loses its largest customer?
- Would the loan still be serviceable without relying on collateral?
Ultimately, credit underwriting is the process of converting incomplete information into a disciplined risk decision.
The strongest credit proposals are not those containing the largest number of ratios. They are the proposals where business purpose, banking behavior, financial statements, cash flow, repayment structure, collateral, management quality and industry risk all tell the same story.
And when they do not tell the same story, that is exactly where the credit analyst’s real work begins.
Remember: Security may protect the bank after default. Cash flow is what prevents default in the first place.