Does a High ROE Really Mean a Stronger Company?
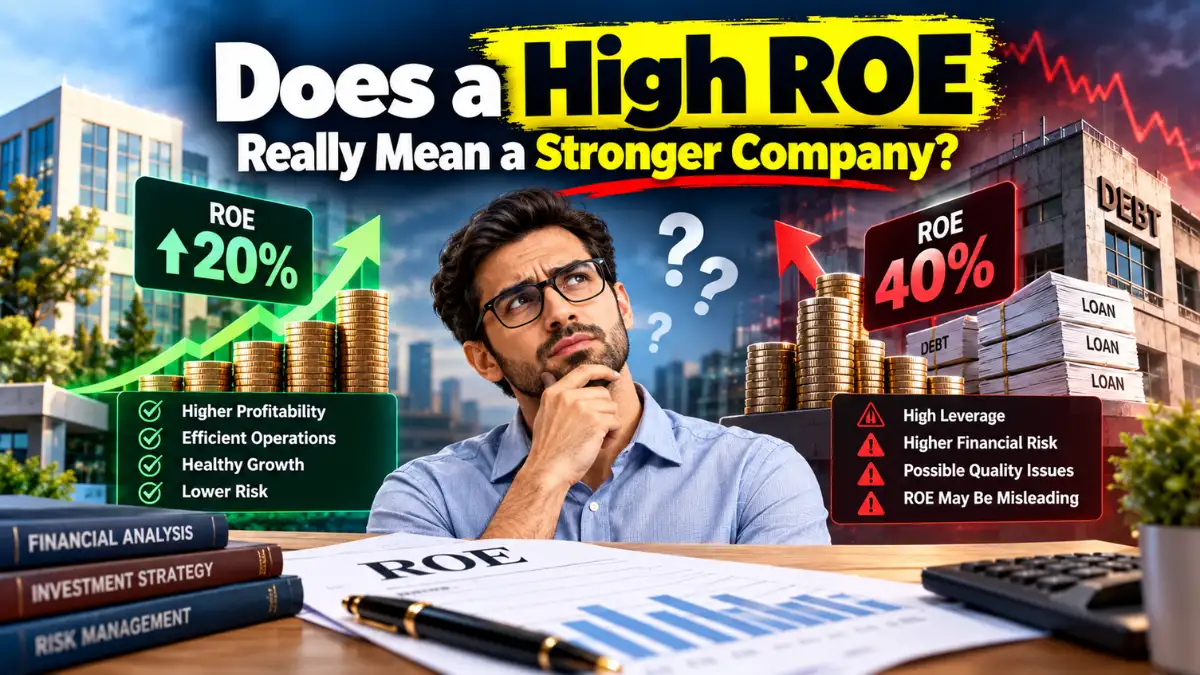
A high Return on Equity (ROE) always looks impressive on paper. But does it really mean a higher ROE is always better? Not necessarily.
From the perspective of investors, one of the indicator to profitability is ROE. It gives us the idea how a company is efficiently generating its profit from its shareholder’s equity. However, looking at ROE alone can sometimes create the wrong impression.
The more important question is not simply “How high is the ROE?” but “Why is the ROE high?”
What Is ROE?
ROE is used a measurement to understand how much profit a company is generating from its investment by its shareholders.
Formula:
ROE = Net Profit ÷ Average Shareholders’ Equity × 100
Consider an example like a Company A has shareholders’ equity of $10 million and earns $1 million in profit.
So its ROE becomes:
$1 million ÷ $10 million × 100 = 10%
This means the company becomes able to generates $10 of profit for every $100 of shareholders investment or equity.
It may seems 20% ROE is better than one with a 10% ROE. But the story can be more complicated at any time.
A High ROE Can Come From High Profitability
Considered the below attached example as best case scenario-
Imagine Company A and Company B both have $10 million of equity.
Company A earns $1 million → ROE = 10%
Company B earns $2 million → ROE = 20%
If both companies have similar debt levels, business risk and accounting quality, Company B’s higher ROE may genuinely reflect stronger profitability.
This is the kind of high ROE investors generally like.
But Debt Can Make ROE Look Better
Now consider another situation with different stories.
Company C has:
- Equity: $5 million
- Debt: $15 million
- Profit: $2 million
Its ROE becomes= $2 million ÷ $5 million × 100 = 40%
That 40% looks excellent.
Now, compare it with a company that has $10 million of equity and $10 million of debt while earning the same $2 million profit. Its ROE is becomes only 20%.
Company C has the higher ROE, but it is also using significantly more debt relative to shareholders’ capital. If business conditions deteriorate, its financial risk could be much higher.
So, a high ROE can sometimes be the result of leverage rather than superior business performance.
What If Equity Becomes Very Small?
This is another reason analysts should be careful.
Suppose a company has:
- Net profit = $1 million
- Equity = $2 million
ROE = 50%
Now imagine another company:
- Net profit = $1.5 million
- Equity = $10 million
ROE = 15%
The first company has a much higher ROE despite generating less total profit.
Why?
Because its equity base is much smaller.
This shows why ROE should never be interpreted without looking at the size and quality of the equity base.
Can a Falling Equity Base Push ROE Higher?
The answer is Yes. Lets take an example of a company which starts with $10 million of equity and earns $1 million.
Then, ROE = 10%
Later on, the company decided to buys back its shares and reduces its equity to $5 million while it is still capable of earning $1 million.
ROE becomes: 20%
The company has not increased its profit at all but still its ROE has doubled. Is the business suddenly twice as good?
The answer is No.
The denominator has changed. This is why analysts should investigate whether a rising ROE comes from higher earnings, lower equity, greater leverage, share buybacks, or a combination of these factors.
High ROE in Banking Needs Extra Attention
For banks, ROE is particularly important—but it should not be viewed in isolation.
Suppose Bank A reports:
- ROE: 18%
- Strong capital position
- Low credit losses
- Stable net interest income
- Healthy asset quality
Now consider Bank B:
- ROE: 22%
- Higher leverage
- Rising non-performing loans
- Increasing provisioning pressure
Which bank is better?
The answer is not automatically Bank B.
A higher ROE associated with deteriorating asset quality means that the bank makes returns by taking more risks. For banks, analysts should look at ROE in conjunction with ROA, capital adequacy, NPL ratio, provisioning coverage, net interest margin, cost-to-income ratio and liquidity indicators
What About a Very Low ROE?
A low ROE does not mean that the company is bad Just take an example of a rapidly growing company that is investing heavily in:
- New factories
- Technology
- Distribution networks
- Research and development
On that times.Its current profits may be relatively low because it is reinvesting heavily. As a result, ROE may looks poor. But if those investments generate stronger profits later than the low ROE could be the part of a long-term growth strategy. This is why context matters.
Compare ROE With the Company’s History
A single year’s ROE tells only part of the story.
Suppose a company’s ROE was:
- 2023: 8%
- 2024: 11%
- 2025: 14%
- 2026: 17%
That trend may be more meaningful than simply saying, “ROE is 17%.”
Now imagine another company:
- 2023: 22%
- 2024: 19%
- 2025: 14%
- 2026: 9%
Although its current ROE may still look reasonable, the declining trend deserves attention. Direction can sometimes be more informative than the number itself.
Compare ROE With Competitors
ROE also needs industry context.A 12% ROE may be impressive to one industry but average to another.
For example, comparing the ROE of a commercial bank directly with that of a software company would not offer much insight as their capital structure, requirements in terms of assets and business model are completely different.
A better approach is to compare companies with:
- Similar business models
- Similar markets
- Similar risk profiles
- Similar accounting structures
The Real Question: Where Is the ROE Coming From?
A useful way to think about ROE is to break it into three broad drivers:
ROE = Profit Margin × Asset Turnover × Financial Leverage
This framework helps analysts understand whether ROE is being driven by:
- Higher profitability
- More efficient use of assets
- Greater leverage
For example, two companies can both have a 20% ROE while reaching that number through completely different strategies.
Company A may have excellent profit margins and moderate debt.
Company B may have lower margins but much higher leverage.
The headline ROE is identical—but the underlying risk is not.
A Simple Real-Life Example
Let us take two small businesses.
Business A: the Efficient Shop
Owner investment: $100,000 and earns $20,000.
ROE: 20%
The business has a small amount of debt and a healthy cash flow.
Business B: the Highly Leveraged Shop
Owner investment: $50,000 but borrows another $150,000.
The business also earns $20,000.
ROE: 40%
Business B appears twice as profitable from the owner’s equity perspective.
But it also carries significantly more debt.
If sales suddenly fall, Business B may face greater pressure from interest and debt repayments.
So which business is better?
The answer cannot be determined from ROE alone.
What Should Investors Check Alongside ROE?
Before concluding that a high ROE means a company is attractive, investors should consider:
- ROA – Is the company generating profit efficiently from its assets?
- Debt-to-Equity – Is leverage contributing to the high ROE?
- Profit Margin – Is the company genuinely profitable?
- Cash Flow – Are reported profits supported by cash generation?
- Asset Quality – Are assets productive and healthy?
- Earnings Trend – Is profitability improving or deteriorating?
- Dividend Policy – Is capital being returned sustainably?
- Industry Average – How does the company compare with peers?
- One-off Gains – Is ROE temporarily boosted by exceptional income?
- Share Buybacks – Has reduced equity artificially increased ROE?
Final Takeaway
- A higher ROE is attractive—but it is not automatically proof of a better company.
- A strong Return on Equity can be generated by a combination of stable profits, efficient operations, a strong cash-flow position and prudent leverage.
- However, a high ROE driven primarily by excessive debt, shrinking equity, exceptional profits or aggressive financial engineering can be quite misleading.
- The key is that instead asking the questions “Which company has the highest ROE?”
- one should be asking“What is driving the ROE, and is that driver likely to be sustainable?”
That is where financial analysis goes beyond simply reading a ratio. A ratio gives you a number. Understanding the reason behind that number gives you the real story.